
Study Guide
Incoterms® as a determination of delivery
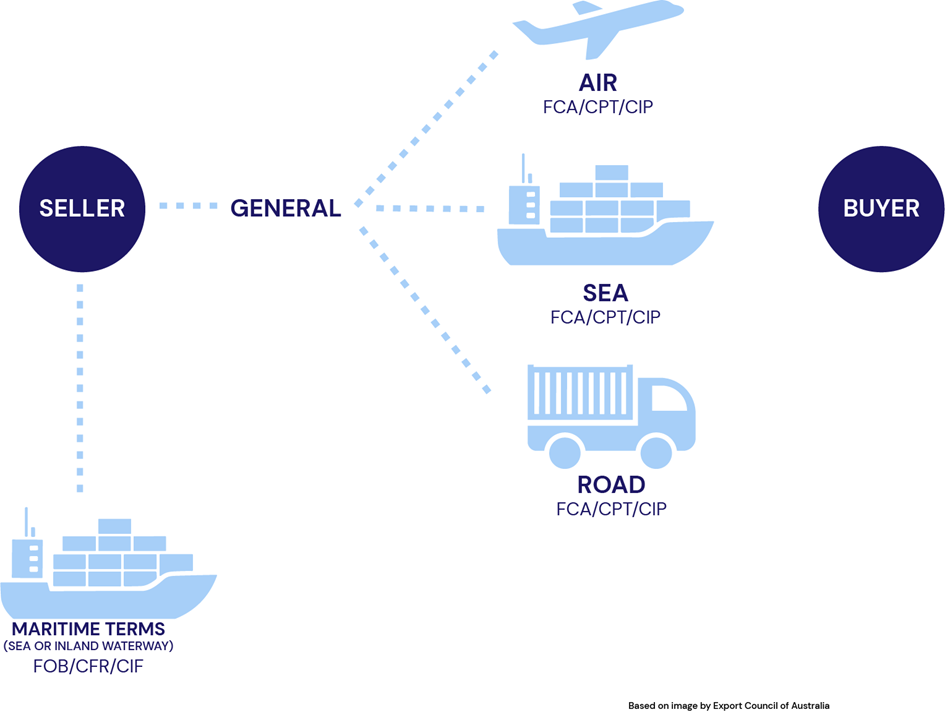
The terms agreed by the seller and buyer define the exact point at which risks and responsibilities pass from one party to the other — in other words, which steps in moving the goods from Point A to Point B are the seller's obligation, and which are the buyers. The same applies to the costs incurred in moving or administering the movement of cargo up to the agreed point. Separate terms apply to general transport and to maritime transport.
|
Note The point of handover is always a physical location. As a general rule:
|
Incoterms® function as abbreviations or shorthand — a series of expressions intended to state each party's obligations clearly and to minimize the potential for disputes.
Incoterms® should be expressly incorporated into the contract of sale and should include the words "Incoterms® 2020" after the trade abbreviation — for example, "FOB Singapore (Incoterms® 2020)". The named place attached to the Incoterm is critical. It will:
- identify either the place or port where goods are considered 'delivered' by the seller to the buyer, or
- identify the place of 'delivery', or
- identify the place or port to which the seller must arrange carriage (the destination) or, in the case of D-rules, both.
Incoterms® are also relevant to customs valuation, which is addressed in a separate module. In most countries, customs duties are levied on a Cost, Insurance and Freight (CIF) basis, meaning that overseas freight and insurance costs are included in the customs value. Where a contract is on Free on Board (FOB) terms, additions must be made to the contract price before a transaction value can be determined.
|
Note Incoterms® cannot address every circumstance and must always be used in conjunction with other trade instruments, including the contract of sale. One significant exclusion is the issue of ownership: Incoterms® govern possession, not ownership. |
The Incoterms® Rules cover obligations in a set of ten paired articles, numbered A1/B1 through A10/B10. Articles A set out the seller's obligations; the B articles set out the buyer's obligations.
|
Articles |
Incoterm Rule |
|
A1/B1 |
General Obligations |
|
A2/B2 |
Delivery/Taking Delivery |
|
A3/B3 |
Transfer of Risk |
|
A4/B4 |
Carriage |
|
A5/B5 |
Insurance |
|
A6/B6 |
Delivery/Transport Document |
|
A7/B7 |
Export/Import Clearance |
|
A8/B8 |
Checking/packing/marking |
|
A9/B9 |
Allocation of costs |
|
A10/B10 |
Notices |
As an illustration of how these articles operate, consider Article A2/B2 on Delivery. Comparing the rules for DAP and DPU demonstrates the difference in seller’s obligations:
- DAP (Delivered at Place) The seller must deliver the goods by placing them at the disposal of the buyer on the arriving means of transport, ready for unloading at the named place of destination. Delivery is deemed to occur when the goods are placed at the buyer’s disposal, on the agreed date or within the agreed period.
- DPU (Delivered at Place Unloaded) The seller must unload the goods from the arriving means of transport and then place them at the disposal of the buyer at the named place of destination, on the agreed date or within the agreed period.
Reading these two articles side by side, the key distinction is clear: under DAP, delivery occurs on the arriving means of transport; under DPU, the seller is also responsible for unloading. (UK Customs Academy, 2020.)